Key Highlights for Wednesday Morning
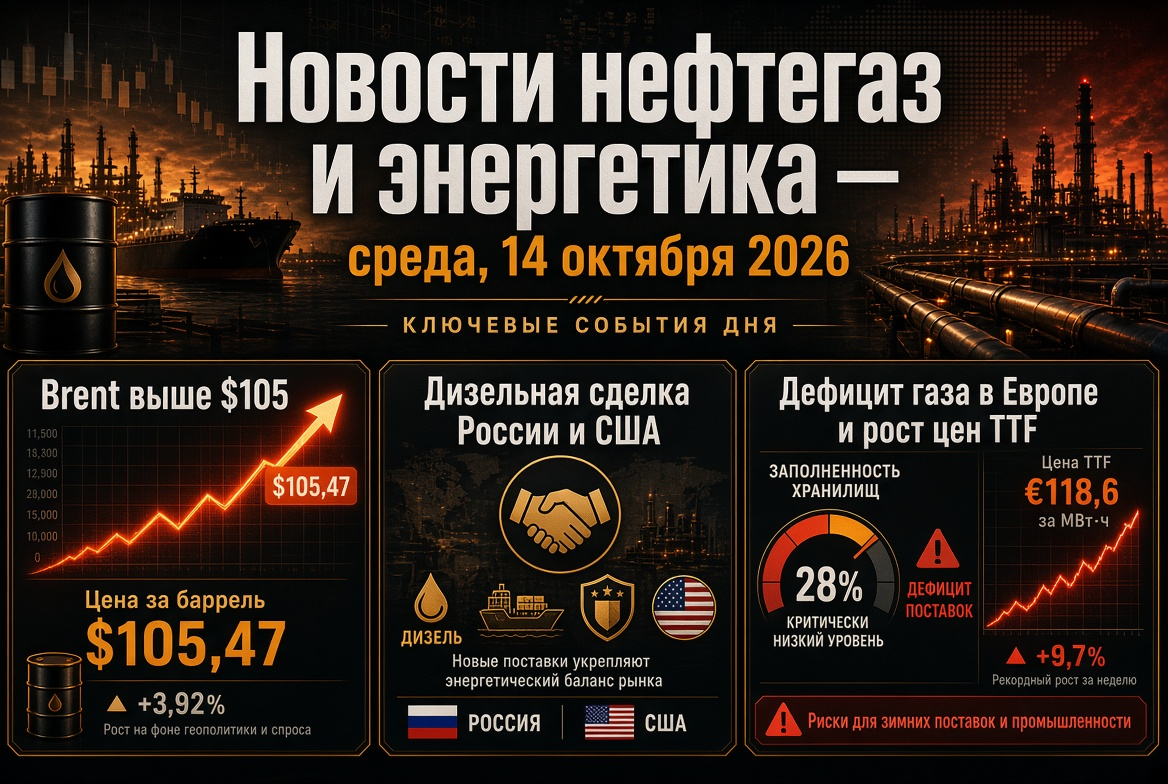
- Oil: Brent is around $105–106 per barrel, WTI is about $93; yesterday, prices climbed above $107.
- Petroleum Products: Russia has partially lifted the ban on diesel exports, releasing 500,000 tons into the global market.
- Gas: TTF is trading around €83 per MWh — the highest since the beginning of 2023; EU storage is approximately 73% full.
- OPEC+: Quotas for November remain unchanged, with the next meeting scheduled for November 1.
- Geopolitics: Attacks on tankers near the Strait of Hormuz and strikes by Houthis on Saudi Arabia continue to pose risks for supply.
Oil Market: Risk Premium Keeps Brent Above $100
On Tuesday, oil corrected by about 1% after a nearly $2 rise on Monday, when Brent closed at its highest since mid-September. The conflict between the U.S. and Iran has been ongoing for eight months, and the market continues to primarily assess the physical availability of barrels rather than the balance of supply and demand.
Supportive Factors
- A drone strike on a tanker near the Omani port of Sohar and damage to another vessel in the Strait of Hormuz; at least nine attacks have been recorded since early October.
- Attacks by Houthis on Riyadh Airport, heightening concerns over Saudi infrastructure.
- High freight and insurance rates, widening the spread between Brent and WTI.
Cont restraining Factors
- Expectations for additional volumes of Russian diesel.
- Recovery of production in the Gulf of Mexico following Hurricane Isaias.
- Weak demand: OPEC has lowered its forecast for oil consumption growth in 2026 to 0.4 million barrels per day from 1.4 million at the beginning of the year.
OPEC+ and Oil Price Forecasts
Seven OPEC+ countries — Saudi Arabia, Russia, Iraq, Kuwait, Kazakhstan, Algeria, and Oman — have maintained a pause on production increases for the second consecutive month, with a total quota of 31.01 million barrels per day for November. Actual production from the alliance remains below target levels due to export restrictions through the Strait of Hormuz.
Analyst estimates are varied:
- Goldman Sachs has raised its Brent forecast for December to $90 from $85, assessing the risk premium at slightly more than $20 per barrel.
- The U.S. Energy Information Administration expects an average of $105 in the fourth quarter and $84 in 2027.
- A consensus poll of analysts gives an average Brent price of around $89 for 2026.
Petroleum Products and Refineries: Diesel Crisis Receives a Breather
The market for middle distillates remains the tightest segment of the energy sector. The gas oil premium to Brent approached $98 per barrel last week: the deficit is more concentrated in refining rather than crude oil. U.S. refineries are operating at about 96% capacity, leaving little room for additional production.
- Russia: As of October 10, the export of 500,000 tons of diesel fuel has been permitted; Washington speaks of the possibility of additional supplies of up to 3 million tons. The U.S. has temporarily lifted sanctions on Russian fuel.
- China: After a week-long pause, Beijing has approved the export of gasoline, diesel, and jet fuel for October at about 3.7 million tons.
- IEA: The agency has urged member countries to accelerate the release of reserves, prioritizing diesel.
Gas oil futures on ICE responded with a decline of 2.3%, down to $1,449 per ton. The effect may be limited: Russian refining has been significantly impacted by drone strikes, and the permitted volume is comparable to one day’s consumption in the U.S. Gasoline prices in the U.S. average $4.36 per gallon.
Gas and LNG: Europe Enters Winter with Record-Low Reserves
The European gas market remains a major source of concern for the energy and industrial sectors. Without Qatari LNG, TTF futures hold near €83 per MWh — approximately 2.5 times higher than a year ago.
- EU storage is 73% full against a seasonal norm of about 90% — the worst level since records began in 2011.
- The target filling level has been softened from 90% to 80%.
- In the event of a cold winter, the bloc may need to reduce demand by 7% or 14 billion cubic meters.
- As of January 1, 2027, a total ban on Russian LNG imports will come into effect.
Forecasts for winter are polarized: from €56 in Citi’s base scenario, where demand has already decreased due to industrial shutdowns, to €85–100 and beyond according to Morgan Stanley in the case of freezing temperatures and new supply disruptions.
Electricity and Renewables: Renewable Generation Mitigates Gas Shock
High gas prices are accelerating structural shifts in the electricity sector. In the first half of 2026, solar generation in the EU set a new record, wind generation increased, and wholesale electricity prices in several countries are increasingly disconnected from gas prices. The downside is a rise in the number of hours with negative prices and evening price peaks, increasing the attractiveness of energy storage investments.
In the U.S., a record installation of about 86 GW of new capacity is planned for 2026, with around 93% of this coming from solar, wind, and batteries. For investors, the renewables and grid infrastructure sector remains a safe haven amid hydrocarbon volatility.
Coal: Demand Supported by Expensive Gas
The coal market is benefiting from the gas deficit. Rising gas prices following the onset of the Middle Eastern conflict have enhanced coal's competitiveness in generation, with energy coal prices in 2026 recovering from lows at the end of 2025. Major demand comes from China, India, and Southeast Asian countries, while in Europe, coal plants serve as a reserve in case of a cold winter. In the long term, volumes of maritime trade in thermal coal are projected to decline, according to industry analysts.
Geopolitics and Sanctions: Energy Truce in Question
The U.S. President announced an energy truce between Russia and Ukraine, yet as early as Monday, Kyiv accused Moscow of violating it. For the market, this means sustained risks for Russian refineries and export infrastructure. Simultaneously, the temporary easing of sanctions on Russian fuel marks the first practical step by Washington to expand petroleum product supply.
What Matters for Investors and Energy Market Participants
- Strait of Hormuz: Every new attack on tankers adds several dollars to oil prices; de-escalation could quickly remove a significant portion of the premium.
- Diesel and Refinery Margins: Actual shipments from Russia and China will indicate whether the petroleum products market has peaked.
- Gas: Weather forecasts for November and drawdown rates from EU storage will determine the dynamics of TTF.
- Statistics: Weekly data on oil and petroleum product inventories in the U.S. and fresh monthly oil market reviews will be in focus.
- OPEC+: The meeting on November 1 will reveal whether the alliance is ready to resume increasing production.
The base scenario for the coming days is high volatility: oil, gas, and petroleum products remain at the mercy of news from the Middle East, while electricity and renewables receive additional momentum from high hydrocarbon prices.