The global energy sector concludes the week amid high volatility. Brent crude oil prices remain above $100 per barrel. Gas prices in Europe are trading at their highest levels since the end of 2022. The diesel fuel market continues to be the most strained segment of the oil and gas industry. For investors, oil and fuel companies, traders, and refinery operators, three key themes prevail:
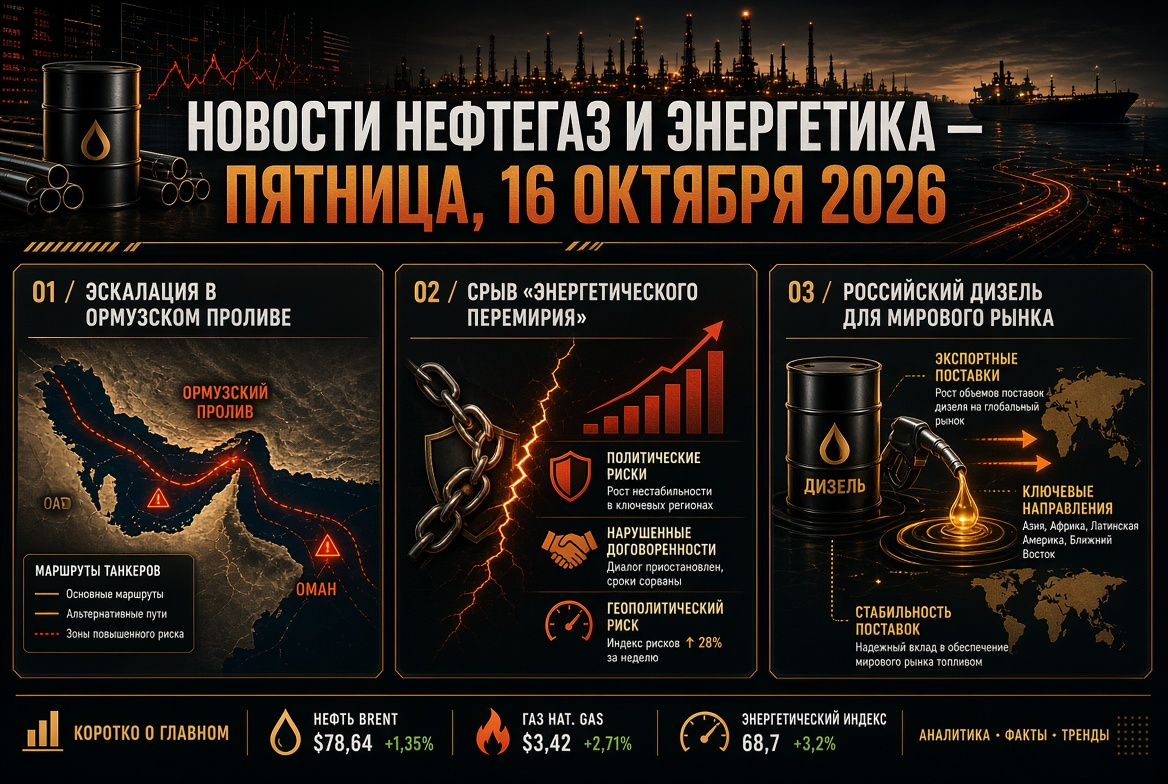
- attacks on tankers in the Strait of Hormuz;
- the deal between Russia and the U.S. regarding diesel fuel supplies;
- the fate of strikes on oil refining infrastructure following the collapse of the "energy truce."
Oil Market: Brent at $104 Amid Expectations of Easing Sanctions Against the "Shadow Fleet"
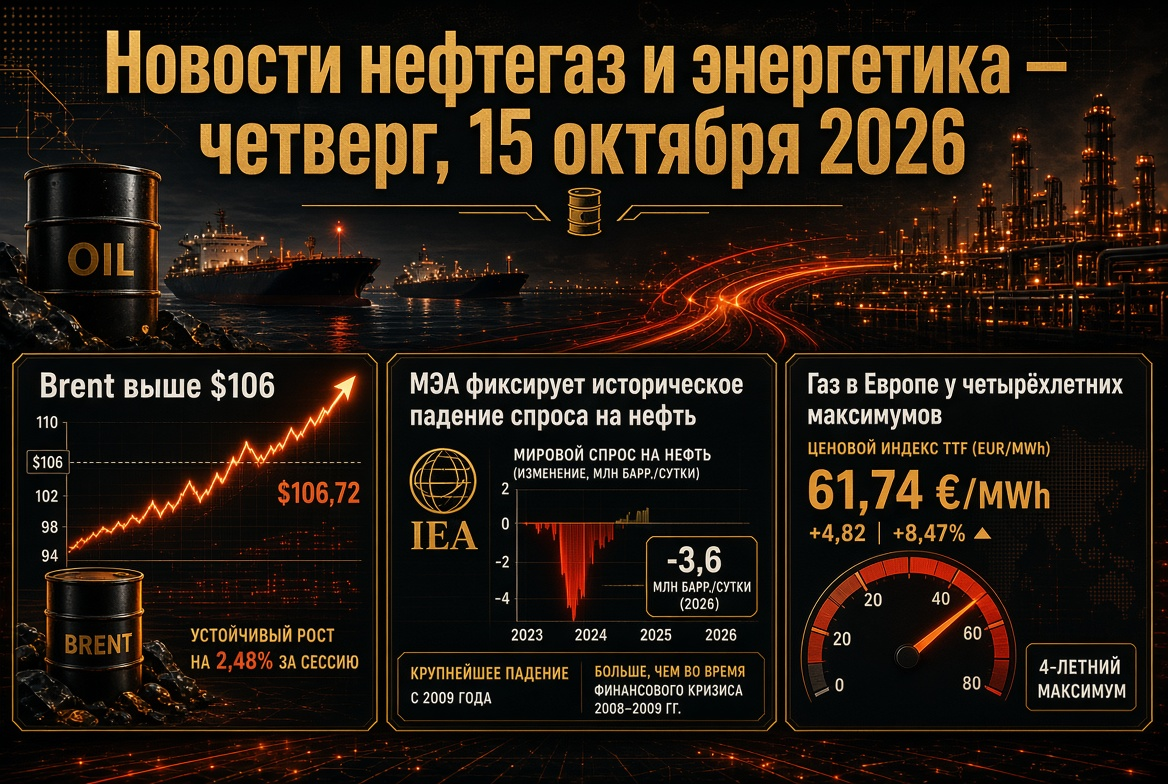
On Thursday, oil prices fell by approximately 2%. The December Brent futures dipped into the $103.5–104 per barrel range after closing Wednesday at $106.06. November WTI is trading around $94–95. Price pressure came from reports that the U.S. administration is considering easing sanctions on vessels from the "shadow fleet." Washington's aim is to reduce record freight rates and expedite oil exports from the Persian Gulf.
Fundamental support for the oil market persists:
- U.S. inventories are declining. According to the American Petroleum Institute, commercial inventories fell by 11.1 million barrels for the week ending October 9.
- Prices remain high year-on-year. Brent is approximately 70% more expensive than a year ago. The annual high of $120.88 was recorded on April 30.
- The Brent–WTI spread has widened. The difference exceeds $9 per barrel, reflecting a risk premium for maritime routes.
Strait of Hormuz: Most Dangerous Phase for Shipping Since War Began
October has become one of the most tense months for the tanker fleet since the onset of conflict concerning Iran at the end of February. This week, two vessels sank, including the Singaporean container ship GFS Pride. Since the beginning of the week, the Strait has recorded at least nine attacks. Tankers carrying crude oil, LNG, and LPG are under fire.
- In September, crude oil exports from the Middle East nearly returned to pre-war levels, facilitated by nighttime tanker transits under the escort of the U.S. Navy with disabled transponders.
- Iran is intensifying pressure to regain control over flows. On certain days, transits through the Strait are reduced by half or more.
- This scenario means that insurers and chartering companies will continue to face record rates and military surcharges.
OPEC+: Quotas Frozen, Actual Output Below Targets
At the October 4 meeting, seven key OPEC+ participants kept their November quotas unchanged. The group includes Saudi Arabia, Russia, Iraq, Kuwait, Kazakhstan, Algeria, and Oman. Target levels are approximately 10.5 million barrels per day for Saudi Arabia, 9.9 million for Russia, and 4.4 million for Iraq.
- The actual output of the alliance's core in August was around 25 million barrels per day, which is approximately 5 million barrels per day below pre-war levels.
- There are still around 2 million barrels per day of cuts in effect.
- The secretariat is completing an audit of maximum capacities, which will be used to calculate the baseline levels for 2027.
- The next meeting is scheduled for November 1.
IEA Report: Oil and Diesel Deficits to Persist Until 2027
The October report from the International Energy Agency confirms that the global oil market balance remains deficit-driven.
- Global oil demand is projected to decline by 2.6 million barrels per day by 2026, to 102.4 million.
- Supply is expected to drop by 5.8 million barrels per day over the year.
- The forecast for demand recovery in 2027 has been downgraded from 2.6 to 2 million barrels per day.
- Refinery utilization is expected to drop to a seasonal low of 81.3 million barrels per day in October, with an anticipated increase to 84.6 million by year-end.
The main risk for refineries and fuel companies is the middle distillates. According to the agency's estimates, global diesel exports have fallen by about 700,000 barrels per day. Tension in the gas oil market is expected to continue until 2027.
Russia-U.S. Diesel Deal: New Flows of Oil Products
The main topic in the oil product market is the agreement between the presidents of the U.S. and Russia on October 9 regarding the supply of Russian diesel fuel to American and global markets. The U.S. Treasury has issued a temporary license for transactions involving Russian diesel until April 7, 2027.
- Volumes: 300,000 tons in October, 500,000 tons in November, 1 million tons in December. Ultimately, volumes could reach up to 3 million tons per month.
- Regulation in Russia: Export restrictions on diesel are being lifted early. The ban on gasoline exports remains in effect until January 31, 2027. The government is also discussing restrictions on LPG exports.
- Supply Mechanism: According to Alexander Novak, the energy ministries of both countries are coordinating a contract and delivery mechanism that takes into account the sanctions against the largest oil companies in Russia.
- Market Reaction: Diesel futures in the U.S. fell by approximately 5%. In Europe, the impact was short-lived since volumes are insufficient to offset the shortfall caused by the crisis in the Persian Gulf.
Refineries and "Energy Truce": The Pause is Over
The "energy truce" announced on October 11 between Russia and Ukraine has effectively been disrupted. Kyiv paused strikes on Russian refineries for three days. Subsequently, Ukraine accused Moscow of a massive attack on its energy infrastructure and announced the resumption of strikes. Just in September, 12 major Russian refineries were targeted. Capacities that are halted or operating at reduced throughput represent nearly a quarter of Russian refining. For oil product exporters, this poses a key risk: the volumes from the diesel deal are directly dependent on the state of the refineries.
Gas and LNG: Europe Enters Winter with Low Stock Levels
The European gas market remains under pressure. TTF futures are trading around €85–87 per MWh, the highest since December 2022, and nearly three times higher than the level a year ago.
- EU underground storage is filled to about 73–74% against a five-year average of approximately 89%.
- Brussels has softened the storage filling target from 90% to 80%.
- Qatari LNG supplies to Europe are virtually non-existent. The Asian JKM indicator exceeds $25 per MMBtu, and Europe is competing with Asia for every cargo.
- Some analysts, however, expect a correction. Citi's baseline forecast for Q4 stands at €56 per MWh.
Coal, Power Generation and Renewables: Two Poles of Energy Security
High LNG prices are bringing coal back into the energy mix in Asia. The price of Newcastle thermal coal hovers around $150 per ton. In early October, it peaked at $152.20, the highest since October 2024, and has risen approximately 45% year-on-year.
Concurrently, the growth of renewable energy is accelerating:
- In Australia, rooftop solar installations set a generation record of 17.5 GW on October 11, with solar accounting for 72% of consumption;
- Australian renewable energy projects with approved investment decisions in 2026 have surpassed 5 GW, setting an annual record;
- In Europe, energy companies are combining solar generation with storage solutions to reduce dependence on gas during peak hours;
- On October 29, the IEA will present its Renewables 2026 report with updated capacity forecasts.
Key Points for Energy Sector Investors on October 16
- Strait of Hormuz. New incidents could quickly drive Brent back to $107–110 per barrel.
- Sanctions on the "shadow fleet." An official decision from the U.S. could reduce freight rates and pressure oil prices.
- First shipments of Russian diesel. These will serve as indicators for crack spreads and refining margins.
- Corporate Agenda. Gazprom Neft is issuing yuan-denominated bonds on October 16 at an interest rate of 8.3%. Stocks of Sovcomflot respond to signals of sanction easing.
- Political Calendar. Ahead of the U.S. midterm elections on November 3, Washington will seek to lower fuel prices.
Week's summary: the global oil, gas, and petroleum products market remains a seller's market. Geopolitical premiums, diesel deficits, and low gas stocks in Europe are supporting prices. Easing sanctions and new logistics schemes only partially mitigate the tension. For market participants, effective risk management remains a key tool.